Benefit vendors are the insurance carriers, third-party administrators, and brokerage firms that growing companies rely on to deliver health coverage, retirement plans, and other workplace benefits. Choosing the right benefit vendors affects employee satisfaction, budget predictability, and compliance exposure all at once, yet many founders and HR leaders inherit these relationships without ever stopping to ask whether they still fit the company. This guide walks through what benefit vendors actually do, how to evaluate them, and when it makes sense to make a change.
Quick answer: Benefit vendors are the carriers, brokers, and administrators who sell or manage employee benefits on an employer’s behalf. The right fit depends on your company size, plan complexity, and how much service support your internal team needs.
Comparing proposals side by side helps employers evaluate benefit vendors on more than price alone.
What Are Benefit Vendors?
Benefit vendors are companies that design, insure, or administer the employee benefits a business offers, typically health insurance, dental and vision plans, retirement accounts, and voluntary benefits like life or disability coverage. Some benefit vendors are insurance carriers themselves. Others act as brokers or third-party administrators who manage enrollment, billing, and compliance tasks on the employer’s behalf.
In practice, a mid-sized company might work with a health insurance carrier, a separate retirement plan recordkeeper, a COBRA administrator, and a broker who coordinates all of it. Each relationship comes with its own contract, renewal cycle, and service standard. According to U.S. Bureau of Labor Statistics data, benefits make up roughly 30 percent of total employee compensation costs for private employers, which is one reason vendor selection carries real financial weight. For a deeper look at how vendor relationships are structured, see this overview of what growing companies need to know about benefits vendors.
Types of Benefits Providers Growing Companies Work With
Not every benefits provider plays the same role. Specifically, employers typically encounter four categories, and understanding the difference helps clarify who to call when something goes wrong.
- Insurance carriers underwrite and pay claims for medical, dental, vision, and life coverage.
- Brokers shop the market, negotiate rates, and represent the employer during renewals.
- Third-party administrators (TPAs) handle claims processing, COBRA, and plan administration for self-funded or complex plans.
- Platforms and outsourced HR partners integrate enrollment, payroll coordination, and compliance tracking into one ongoing relationship.
As a result, a company with 10 to 250 employees often ends up juggling several of these providers at once. In contrast, larger enterprises typically have internal benefits staff dedicated to the task. To understand what separates a strong provider from an average one, review this guide on what makes a benefits management service stand out for small companies.
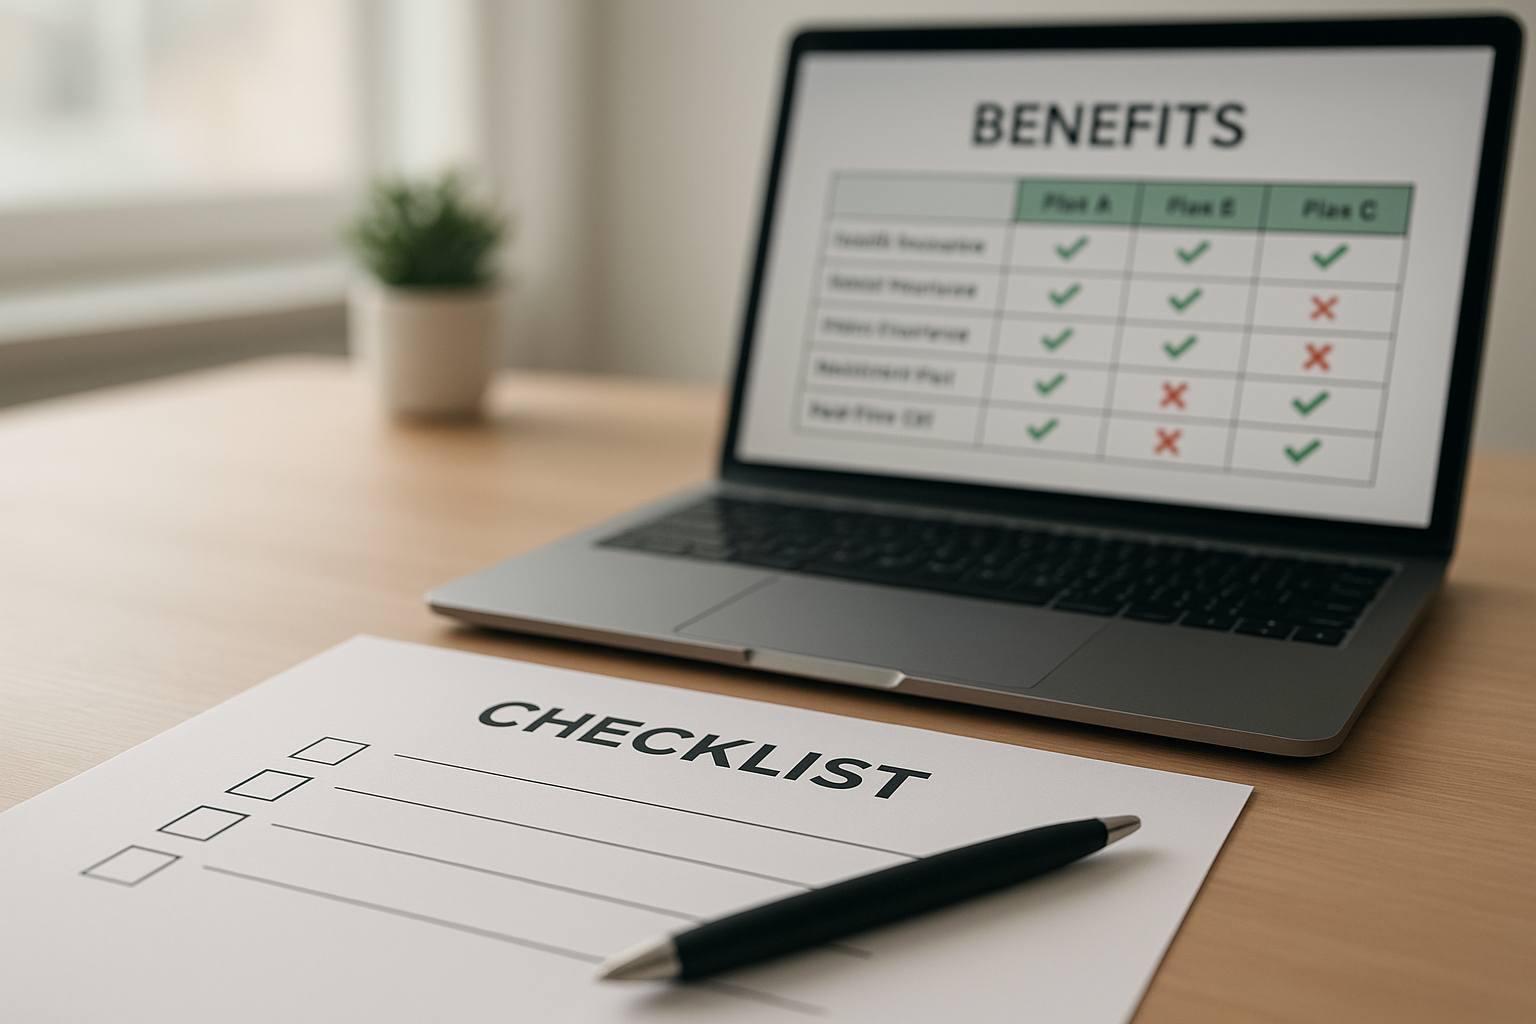
A structured checklist keeps the vendor evaluation process consistent and fair.
How to Choose the Right Benefit Vendors
Choosing the right benefit vendors is rarely about finding the lowest premium. Instead, it comes down to matching service capacity, compliance support, and plan design to your actual workforce. The following steps outline a practical process.
- Define coverage priorities and budget. Document which benefits matter most to your workforce, such as medical, dental, retirement, or voluntary coverage, and set a realistic budget range before contacting any vendor.
- Request proposals from multiple vendors. Gather quotes from at least three benefit vendors so you can compare plan networks, pricing tiers, and service models side by side rather than evaluating one option alone.
- Check financial strength and references. Review carrier financial strength ratings, confirm broker licensing, and ask each vendor for references from clients of similar size to verify they deliver on their promises.
- Review service-level commitments. Read the service agreement closely to understand enrollment support, claims escalation turnaround, renewal notice timelines, and who you will contact when problems arise.
- Confirm compliance support in writing. Ask each vendor to specify exactly which ACA, COBRA, Section 125, and Form 5500 support tasks are included, since employers remain responsible for any gaps.
Common Mistakes Employers Make When Evaluating Benefits Partners
Even careful employers fall into familiar traps. For example, many select a provider based on premium alone, without weighing service responsiveness or claims turnaround. Others renew automatically year after year, assuming loyalty earns better treatment, when in fact rates often creep upward without a competing bid in the market.
Furthermore, some companies fail to confirm who actually handles compliance tasks like COBRA notices, discovering only after a missed deadline that the vendor’s scope did not include it. Above all, skipping reference checks is a recurring misstep; a vendor’s sales pitch rarely reflects what day-to-day service actually feels like once the contract is signed.
Benefit Vendors vs. an Outsourced HR Partner
Benefit vendors sell or administer a specific product. In contrast, an outsourced HR partner coordinates across all of those vendors, handling enrollment communication, carrier coordination, and compliance tracking as part of a broader HR relationship. Many growing companies find that managing four or five separate vendor contacts becomes its own part-time job.
That is why some employers choose to outsource benefits administration rather than manage every vendor relationship internally. An Administrative Services Organization (ASO) model, for instance, lets a company keep full control as the employer of record while gaining dedicated support for employee benefits administration tasks that would otherwise fall to an already-stretched internal team. Soteria HR, based in Pasadena, California, supports employers across Los Angeles, Orange County, and nationwide through this kind of ASO arrangement, without creating a co-employment relationship.
Clear communication during open enrollment eases the transition when a company changes benefit vendors.
Signs It May Be Time to Switch Your Benefits Vendor
Several warning signs suggest a vendor relationship has outgrown its usefulness. Specifically, watch for slow claims resolution, unexplained premium increases above market trend, limited plan options as headcount grows, or a broker who disappears between renewals.
Similarly, if your company has grown past 50 or 100 employees since the last vendor review, the plans that once fit may no longer be competitive for recruiting. A stronger benefits strategy can directly support hiring goals; see this explanation of how a benefits provider can help attract better employees. Therefore, a periodic, honest review against the current market is worth the time it takes.
If an internal review raises more questions than answers, a free HR Health Assessment can help surface benefits and compliance gaps before they become costly, and the results can guide a more focused conversation with Soteria HR.
Frequently Asked Questions About Benefit Vendors
What are benefit vendors?
Benefit vendors are insurance carriers, brokers, third-party administrators, or platforms that design, sell, or administer employee benefits such as health coverage, retirement plans, and voluntary benefits on behalf of an employer.
How do benefit vendors differ from insurance brokers?
A broker is one type of benefit vendor who shops the market and negotiates on an employer’s behalf, while other benefit vendors, like carriers or third-party administrators, underwrite coverage or handle day-to-day administration directly.
How much do benefit vendors typically charge?
Costs vary widely by vendor type and plan design. Brokers are often paid through carrier commissions, while administrators or platforms may charge per-employee-per-month fees in addition to plan premiums.
How long does it take to switch benefit vendors?
A typical transition takes roughly 60 to 120 days to allow time for plan comparisons, carrier approvals, and employee communication. Consequently, most employers time a switch to coincide with their renewal date.
What questions should I ask a potential benefits vendor?
Ask about plan network breadth, renewal rate history, service-level guarantees, and who handles claims escalations. In addition, confirm exactly how the vendor supports compliance tasks like ACA reporting.
What mistakes do companies make when choosing benefit vendors?
Common mistakes include choosing on price alone, skipping financial strength checks, overlooking service responsiveness, and failing to call references from similarly sized clients before signing.
Can a small business work with multiple benefit vendors at once?
Yes. Most employers coordinate several benefit vendors at the same time, such as a medical carrier, a dental carrier, and a retirement recordkeeper. As a result, many rely on a broker or outsourced HR partner to keep everything aligned.
How often should we review our benefit vendors?
A formal review at every renewal, typically annually, is standard practice. In addition, a deeper evaluation every two to three years helps confirm the vendor still fits the company’s size and needs.
What happens if a benefit vendor fails to meet compliance requirements?
Employers remain responsible for compliance even when a vendor makes an error. Therefore, a missed COBRA notice or ACA filing can still result in penalties for the company, not just the vendor.
Do benefit vendors handle COBRA and ACA reporting?
Some benefit vendors, particularly third-party administrators, offer COBRA and ACA reporting support. However, the scope varies by contract, so employers should confirm exactly what is included before signing.
How does outsourced HR support benefit vendor management?
An outsourced HR partner can coordinate between carriers, brokers, and payroll, manage enrollment communications, and flag compliance gaps. This reduces the administrative burden placed on internal staff.
What size company needs a dedicated benefits vendor strategy?
Companies with roughly 10 to 250 employees often benefit most from a deliberate strategy, since they are large enough to have meaningful benefits costs but may not yet have dedicated internal benefits staff.
Why might a company outsource benefits administration instead of managing vendors internally?
Outsourcing gives growing companies access to staff who already know how to vet benefit vendors, manage renewals, and handle compliance, without the cost of building a full internal benefits department.
Not sure where your current vendor relationships stand? Soteria HR helps growing employers in Los Angeles, Orange County, and nationwide evaluate and manage benefit vendors as part of a broader HR partnership.
Call (800) 399-2458 or submit a consultation request to talk to an HR expert.
Choosing the right benefit vendors is an ongoing responsibility, not a one-time decision made at launch. In summary, employers who regularly compare proposals, check service standards, and confirm compliance support in writing are far less likely to face surprises at renewal time. Above all, remember that no vendor relationship should be treated as permanent simply because it has existed for years. As your company grows, your benefit vendors should grow with it, and if they do not, it is a reasonable signal to start a broader review.